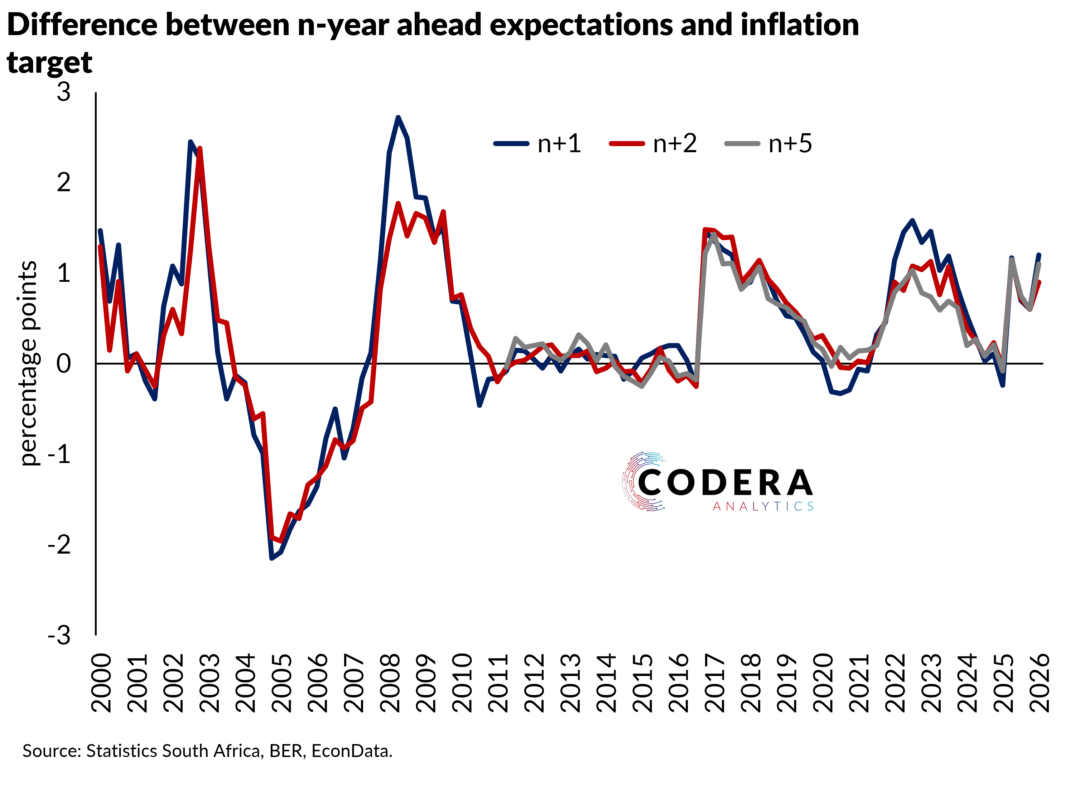
Today’s post by Jurgens Fourie compares the correlation of different inflation expectations measures to headline inflation, and over pre- and post-2017 subsamples. The charts show that the correlation between deviations in survey-based expectations from the inflation target have become more highly correlated to deviations in headline inflation from target since the SARB shifted to communicating a preference for the midpoint of its inflation target in 2017. Well anchored inflation expectations should remain unresponsive to short term inflation fluctuations. It is also interesting that the correlation of market-based expectations have generally been lower.
It is important to note that there are many ways to measure how anchored inflation expectations are. We have shown in earlier posts that expectations remain heavily tied to current spot inflation rather than fully anchored to the target. The SARB’s interest rate formula in its forecasting model is also not based on contemporaneous correlation between expectations measures. In our latest Policy Brief we swap out the SARB’s expected inflation series and neutral estimates in its Taylor rule for our market-implied estimates. We demonstrate that if one were to base expected inflation on market-based measures instead of survey-based measures, then policy would need to tighten to ensure that it will achieve a 3 percent target over the medium-term.